

H1 Update
The portfolio was up 10% in the first half of 2026, measured in SEK. There is little new to report and there were no meaningful portfolio changes during the quarter - or even during the first half. I am very happy with this kind of performance, as I am loosely aiming for 15% per year. Year to date, the portfolio is up around 19%.
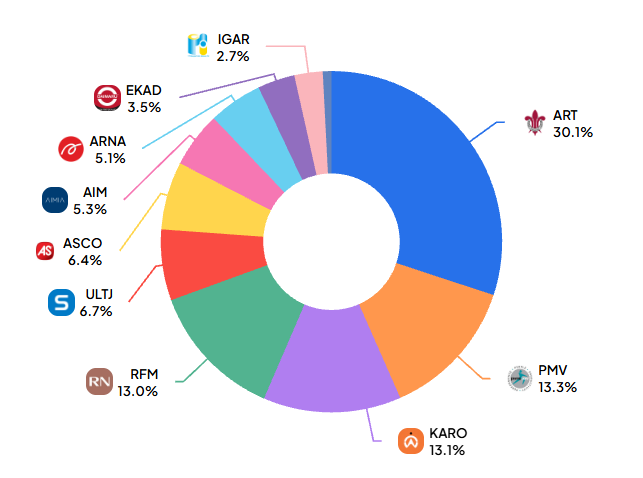
The main drivers have been Argent and Karooooo, but RFM and AS Company have also performed quite well. Most importantly, none of the holdings has suffered a major drawdown. Currency movements have had a small positive effect, and the strong dividend contributions should not be overlooked.
This is how the portfolio looks at the time of this writing:
Why Aimia? My view in short
After H1, I bought into Aimia, as mentioned in an earlier note. My thesis for Aimia is extremely simple:
Rhys Summerton is underrated and not widely known, but a very good capital allocator (in my view). He also has the right incentives, since he owns a significant amount of Aimia.
The company is quite cheap and has some structural advantages, although not unique ones.
The strategy is good. I would call it sophisticated simplicity. I am not sure about execution yet, but it’s the serial acquirer story with a twist: acquiring listed and unlisted businesses through a modern, Graham-like value framework with a hint of activism and a preference for net cash companies.
I have started with a small position. The money came partly from cash but mainly from a reduction in Karooooo. Why did I reduce? Well, it has had a very strong run, and on top of that, Zak disclosed on Nasdaq’s website that he intended to reduce his stake. Karooooo remains a large holding, but it is back around the weight it had earlier this year. These decisions are difficult to make. It is the constant struggle, discussed earlier, between deep value and GARP.
Disclaimer: I own shares in Aimia, and everything I write here reflects my own interpretation. I may have gotten some things wrong - that happens. I am happy to be corrected or challenged where appropriate. It’s 100% my words, not Aimias.
A few good writeups
Aimia is relatively unknown outside Canada, but I am actually a little late to the small but dedicated “write about Aimia on Substack” party. I recommend reading these write-ups about Aimia. I agree with the general view presented in these write-ups, sorted by publication date:
Hugo Vikström (use translate)
But above all, read the management information circular (Letter from the Executive Chairman) for Rhys Summerton’s own description of Aimias history and intended future. This 2025 Milkwood-interview may also be important to read.
My view in more detail
Background
The starting point for my interest in Aimia is that I “know” Rhys in a sense, having been an Argent shareholder for five years. I have at least seen what he has done, together with Treve Hendry. Aimia is, to some extent, a bet on Rhys.
This is also an investment where the phrase “past performance is not a reliable indicator of future performance” is actually a positive for Aimia. My checklist says that a company should not have a history that scares you. But this is a new company operating under the old name and “new Aimia” is more unproven than the other companies I own. It’s a bit like when a mismanaged soccer team gets new owners, new manager, a new strategy, and start applying common sense. Given time, things will change to the better.
Reading the management information circular, this is almost exactly what I like: buying small, cheap, net-cash companies, and maybe taking some of them private (to increase FCF yield by removing listing costs). And why not target orphaned listed stocks, particularly in the UK, that trade even more cheaply than private companies - especially after taking their cash into account? And then improve them, mostly by better capital allocation. That is a very good, simple idea.
The low-risk serial acquirer model
In Argent’s history, and potentially in Aimia’s future transactions, I see the serial-acquirer model being applied sensibly and adapted to low - or really quite normal- risk-taking. Here I may be a bit critical to the concept of serial acquirers, perhaps too much, but I want to make a point how different Argent, and probably Aimia is.
There is a great deal of interest (sic!) in the serial-acquirer model. But if you invest in a “normal” serial acquirer I think you face two typical risks:
High valuation
High debt
First, I think there is a popularity premium, at least if you go for companies i e listed in Sweden where this is a thing. I understand the attractive elements but think there are hidden risks. To start with: Why should a company buying ten P/E 10 companies “magically” be valued at P/E 30. A collection of 10 mediocre businesses should perhaps have a more mediocre valuation, despite increased diversification?
Secondly, for some unclear reason, most companies are burdened with debt and are neither agile nor prepared to act during difficult times. Some are not even self-sufficient or shock resistant and it is rather unhealthy. They almost live on a diet of debt and share issuances - the opposite of cannibalism. Despite the somewhat disgusting name, “cannibals” are healty companies that reduce their share count.
In some cases there are additional risks:
additional popularity premiums;
“100-bagger” status for mysterious reasons;
corporate-governance concerns;
high debt combined with cyclicality;
Compulsory buying even if no good deals.
It does not make sense to me why some serial acquirers are - or have been - so popular. But I think Aimia, post-2025, does make sense. Aimia could resemble early Buffett-style investing, without the obligatory Buffett quotations that so many companies like to use. The focus on net cash, low valuations, FCF yield and old-school, out-of-favour book value is refreshing. Graham might have liked it.
Is there really an edge, owning this?
My “edge”- or, less dramatically, my specific knowledge or advantage - is based on the following:
Buying something small and illiquid. Below USD 300 million, many large investors are excluded. One (good) reason why liquidity is so limited is that the board owns around 43% of the outstanding shares. That percentage increases through buybacks.
Knowing the Argent and Milkwood story well, including the blueprint Summerton has followed.
Not having the same emotional history with Aimia’s past. I approach Aimia with a relatively clean slate and can judge the new Aimia without prejudice. (Or maybe there is “positive prejudice” in the form of confirmation bias).
Reading everything I can find about Aimia over the past few months, including listening to the AGM several times. Few investors appear to have done that, since it has 59 views on Youtube and several of them are mine (haha).
Having a good, small network of investors interested in Aimia with whom I can discuss the company - and, of course, reading and thinking carefully about the Substack write-ups.
None of these points is especially unique. But taken together, they are necessary for me to build conviction in something that remains somewhat unproven and new. Conviction is a bit harder for this one. Nine out of ten stocks I buy screen well. Aimia does not. But it is cheap, and it is promising. I strongly support what they are trying to do: Finding inefficiencies in the markets and capitalize on those. For now I have trust in management. I think things will be clearer after a few deals.
And the management is not spinning stories. They could have talked about SpaceX as a customer of their rope business, but they don’t. They remain firmly on Earth. I actually like the rope business. In one sense, it is a “picks and shovels” investment - except here it is picks, shovels and ropes. Overall, this management prefers ropes over rockets, and I share that view.
Confirmation bias risks
Like me, Rhys prefers really cheap companies and dislikes debt. He looks at unusual places, like UK and South African microcaps. I know that the similarities end there: he is good, while I am trying to become good one day. But Rhys is one of very few global managers interested in - and owning - Argent Industrial, a company that is my absolute favourite stock in the world. I could see at path forward, that Aimia might become “Argent” on a larger, global scale.
That’s a great opportunity, but also a great risk of me getting affected by a few biases. Blueprints and pattern recognition are mostly good but also dangerous. Every time you start referring to an investor only by their first name, that could be a warning sign. So I might stop doing that. Rhys Summerton it is - or simply Summerton. There is, of course also the risk that this case is dependent on one single person. That’s the largest risk.
But I firmly believe that Summerton is genuinely underrated and deserves much more attention from global value investors, and investors generally. He stands for a modern Graham-style investing with a touch of activism, adapted to today’s markets.
Opinions?
What is your opinion about Aimia, and with that I mean “new Aimia”? And what is your view of serial acquirers that don’t rely on debt? I must say that I like both.
I know I am somewhat critical of conventional serial acquirers - perhaps too critical. But compare some of them with Argent and Aimia’s new strategy, and you might become critical too.
Hi Gustavo, I'd like to hear more about why you feel the company is so cheap. As I see it, the company trades around it's SotP NAV in which case you could always buy UK microcaps yourself. Also doesn't this waste the chance to use the NOLs?
“Why Aimia? My view in short”
Doesn’t sound very auspicious for a long position.
HAHAHAHA